Crew accommodation in Germany: can we get the VAT back?
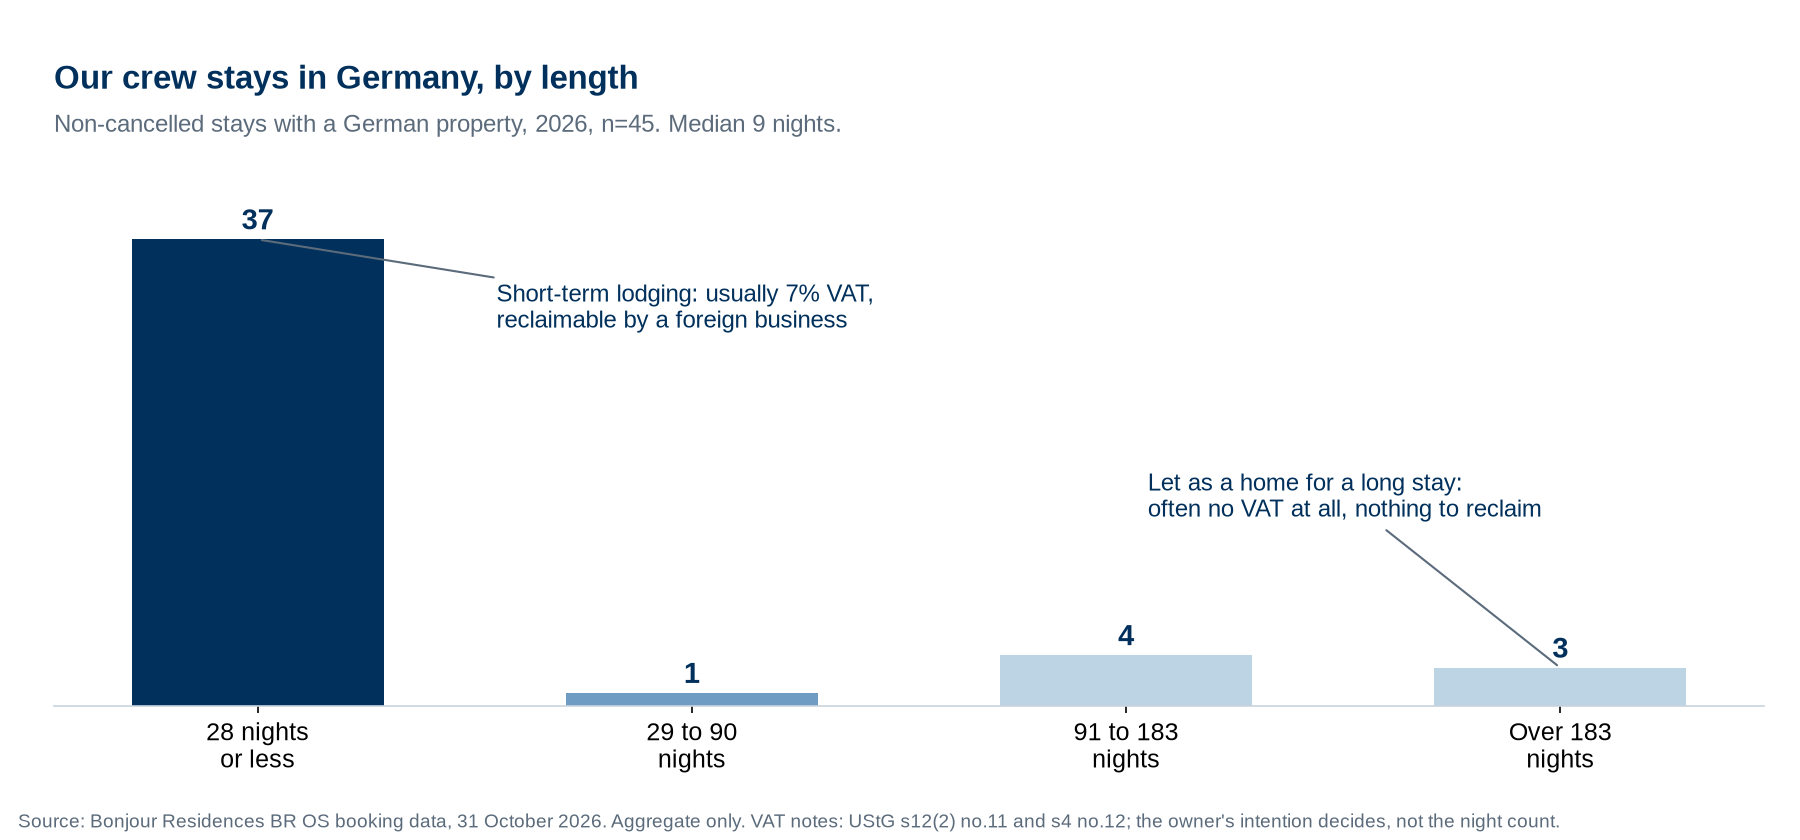
A foreign contractor can usually reclaim the 7% German VAT on short crew stays through the Federal Central Tax Office, but much of it is lost before the claim starts: the invoice is in the wrong name, a long let carries no VAT at all, or the line is a city tax, which is not VAT. UK firms must claim 2026 VAT by 30 June 2027, EU firms by 30 September 2027, and neither deadline is extended. In Bonjour Residences booking data, 37 of 45 crew stays in Germany in 2026 were 28 nights or less, so most German crew invoices are short-stay VAT invoices.
| 37 of 45of our 2026 crew stays in Germany were 28 nights or less | 7%German VAT on short-term lodging; 19% on drinks, wellness and charged parking | 30 Jun 2027deadline for UK firms to reclaim German VAT paid in 2026 | 5%new city tax in Kiel and Rodgau since 1 October 2026, and it is not VAT |
A UK contractor sends a crew of six to a plant upgrade in Hesse for three weeks. The flat invoice arrives with 7% German VAT, a cleaning line, and a city tax. Accounts payable asks one question: can we get the German VAT back?
Usually yes, on paper. In practice a lot of it is lost, and not at the claim. It is lost at booking, when nobody checks whose name goes on the invoice, whether the let carries VAT at all, or which lines are not VAT. Germany is our busiest country, with 45 of our 213 non-cancelled crew stays this year, so the answer matters.
What VAT is on a German crew invoice?
Letting rooms held for short-term lodging is taxed at 7% under section 12(2) no.11 of the German VAT Act. The same rule says the reduced rate does not cover services that do not directly serve the letting, even if they are included in the price. On 1 October 2026 the Federal Fiscal Court published three judgments confirming that breakfast and access to fitness and wellness facilities fall outside the 7% lodging rate, while free parking open to the public is not a paid supply at all. Since 1 January 2026, food in restaurants and catering is back at 7% under a separate rule, but drinks stay at 19%.
A flat let as a home is different. Letting property is exempt under section 4 no.12, and in a case on accommodation for seasonal workers the court restated that furnished rooms let for a permanent stay are exempt too. What counts is the owner's intention, not the night count. And a private owner whose turnover stayed under 25,000 euros last year (and stays under 100,000 euros this year) charges no VAT under the small-business rule. No VAT on the invoice means nothing to reclaim, so compare long-stay quotes on the gross price.
How does a foreign contractor claim it back?
Through the Federal Central Tax Office (BZSt), as long as the company is not registered for VAT in Germany. The route depends on where the company is based.
- EU companies file through their own tax authority's portal by 30 September of the following year. The minimum claim is 400 euros, or 50 euros for a full-year claim.
- UK and other non-EU companies file direct with the BZSt within six months of the year end, so by 30 June 2027 for VAT paid in 2026. The UK qualifies because it refunds German businesses too. The minimum is 1,000 euros, or 500 euros for a full-year claim. Invoices over 250 euros must be uploaded in the BZSt portal (the rule since 1 January 2026, replacing paper originals), with a certificate from the home tax authority that the company is registered as a business.
Both deadlines are final. The BZSt warns that portal access for foreign applicants is posted and can take weeks to months, and a city service page puts registration at four to six weeks and processing at around six months. A firm that starts in June will miss the June deadline.
Why is the city tax not part of it?
Because it is a local tax on the stay, not VAT. More German towns are adding one. Kiel introduced a 5% overnight tax on 1 October 2026, Rodgau did the same that day, and Paderborn started a 3% tax on business and private stays on 1 April 2026. Berlin has taxed business stays at 7.5% since April 2024. Rodgau's own worked example even adds the 7% VAT on top of the city tax. Rules for long stays vary: Kiel exempts stays of more than two months in the same place, and Hamburg only taxes stays under two months. Our German stays are mostly in small towns (more than 30 places this year), which is exactly where these new taxes are appearing. Our earlier piece on tourist tax on crew accommodation covers the rest of Europe.

Which lines can you get back?
| Line on a German crew invoice (2026) | Typical rate | Can a foreign business get it back? |
|---|---|---|
| Room or flat let for short-term lodging | 7% | Yes, through the refund procedure |
| Flat let as a home for a long stay | No VAT (exempt letting) | Nothing to reclaim |
| Private owner under the small-business rule | No VAT shown | Nothing to reclaim |
| Breakfast food | 7% under the restaurant rule since 1 January 2026 | Yes |
| Drinks, wellness or fitness, parking charged separately | 19% | Yes |
| City tax (Übernachtungsteuer, Beherbergungsteuer) | Not VAT, set by the town | No |
What should bookers do differently?
- Put the claiming company on the invoice. Full company name and address, not the crew member or the agency that booked it. A refund claim stands or falls on the invoice. See why invoices get rejected.
- Ask for VAT, city tax and extras on separate lines. It takes the owner a minute at booking and saves your finance team an argument later.
- Compare long stays on the gross price. A flat with no VAT may still be the cheaper option. Our clients have saved 20-30% by using the correct market for the length of stay.
- Register for the BZSt portal now if you are outside the EU. Then file one claim for the year in the spring, well before 30 June.
- Keep the German invoices in one folder per year. Claims run by calendar year, not by project. For the wider rules, read accommodation for workers in Germany.
FAQ
What VAT rate applies to crew accommodation in Germany?
7% on rooms and flats let for short-term lodging. A flat let as a home for a long stay is usually exempt, so no VAT is charged.
Can a UK company reclaim German VAT on hotel and flat stays?
Yes, through the BZSt refund procedure for non-EU businesses, within six months of the year end and for at least 500 euros on a full-year claim.
Can we reclaim the German city tax?
No. It is a local tax, not VAT, so it is a cost of the stay.
Is breakfast taxed at 7% in Germany?
Breakfast food is 7% in 2026 under the restaurant rule. Drinks are 19%.
- Bundesfinanzhof, press release 055/26, Steuersatzermäßigung im Hotel (judgments of 21 May 2026, V R 8/26, V R 10/26, V R 11/26), 1 October 2026.
- Umsatzsteuergesetz, sections 4 no.12, 12(2) no.11 and 19 (as amended by the Jahressteuergesetz 2024), gesetze-im-internet.de, read 31 October 2026.
- Bundesfinanzhof, decision on accommodation for seasonal workers, relationship of section 4 no.12 sentence 2 to section 4 no.12(a) UStG (STRE201350527), bundesfinanzhof.de.
- Bundesministerium der Finanzen, letter of 22 December 2025 on the reduced rate for restaurant and catering services from 1 January 2026; press release of 10 September 2025.
- Bundeszentralamt für Steuern, Vorsteuervergütung: Unternehmer aus EU-Mitgliedstaaten, and Unternehmer aus Drittstaaten (deadlines, minimum amounts, upload rule from 1 January 2026, certificate of status, portal registration), bzst.de, read 31 October 2026; Umsatzsteuer-Durchführungsverordnung, section 61a.
- Bundesministerium der Finanzen, letter of 9 November 2022, list of non-EU states with reciprocity for VAT refunds (United Kingdom since 1 January 2021).
- Landeshauptstadt Kiel, Informationen zur Übernachtungssteuer, from 1 October 2026; Stadt Rodgau, Übernachtungssteuer, kiel.de and rodgau.de, read 31 October 2026.
- Stadt Paderborn, Rat beschließt Einführung einer Beherbergungssteuer (from 1 April 2026); Service Berlin, Übernachtungsteuer; Hamburg Tourismus, Kultur- und Tourismustaxe, read 31 October 2026.
- Bonjour Residences, BR OS booking data, 31 October 2026 (45 non-cancelled crew stays with a German property in 2026, of 213 overall). Anonymised aggregate, no client names or rates.
Contact us today to discuss your next project